The data center build-out is completely changing where construction dollars are going in America. AI and cloud computing require massive amounts of physical space, power, and cooling, and very few markets have seen this to the extent we are seeing now. The owners are all racing to get that capacity online. At the same time, the wider construction market is quite frankly cooling. The net effect is a sharp concentration of capital in one sector.
For facility owners, developers, and industrial contractors, that shift has real implications. Schedules are tighter, power infrastructure requirements are increasing, skilled crews are harder to source, and projects are moving into areas that have never had this type of work before.
Knowing where the money is going enables owners to plan more effectively. It also explains why execution certainty is now as important as budget. DC investment is still rising; manufacturing construction is falling. The power demand from these DCs is on track to more than double. The trades that build them are all stretched. All of this affects how mission-critical projects are planned, staffed, and delivered. Three forces are at work in terms of mission-critical construction:
Concentration of capital.
The rise in power demand.
The growing shortage of skilled labor.
What Is Driving the Data Center Construction Boom
Demand starts with sheer volume. According to Pew Research Center, the U.S. had more than 3,000 operating data centers as of February 2026; at least 1,500 are still under development. Each new facility needs far more power than past generations of commercial buildings. Pew’s review of International Energy Agency data shows U.S. data centers used 183 terawatt-hours of electricity in 2024. That figure is projected to reach 426 terawatt-hours by 2030. Meeting that load requires substations, switchgear, generators, and cooling plants alongside the buildings themselves.
Federal spending data reflects the same pressure. The U.S. Census Bureau reports private power construction at $171.7 billion annually in September 2026 (12.1% higher than a year earlier). Moreover, the Census Bureau counts data centers as part of private office construction. That category reached $145.6 billion, up 39.5% year over year, and has climbed every month since May. Notably, separate estimates put data center construction alone near $85 billion annually as of August.
Geography is shifting, too. In fact, two-thirds of planned data centers sit in rural areas. Nearly 4 in 10 are headed to counties without an existing facility. Texas and Georgia rank second and third in planned projects, behind only Virginia. New regions bring new supply chains, new labor pools and new logistical challenges for every project team.
U.S. Construction Spending Reallocated to Server Halls & Power Projects
The data center construction boom is not lifting every sector equally. Census data shows total U.S. construction spending fell to $2,186.1 billion annually in September, a 2.7% year-over-year decline. Similarly, private residential spending dropped 8.9% over the same period. This data suggests U.S. sector growth is more concentrated than broad.
Manufacturing shows the sharpest contrast. Private manufacturing construction fell to $167.2 billion, a 17.9% decline from a year earlier. That is the steepest drop of any major private category in the September report. Not long ago, new plants drove much of nonresidential growth. Now server halls and power projects lead.
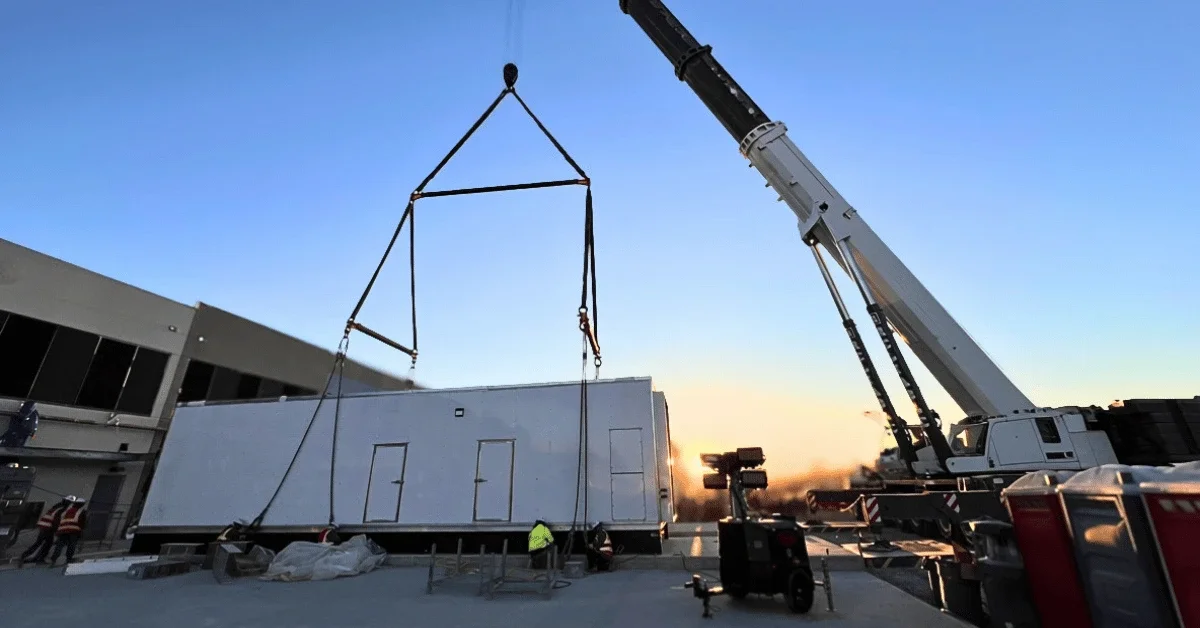
This shift changes the competitive landscape for owners. Mechanical, electrical, and rigging trades are following the capital. Manufacturers planning plant and facility expansions, relocations, or shutdowns now compete with data center developers for the same specialized crews.
The work itself also differs. Data centers demand dense mechanical and electrical systems, precise equipment settings, and tight commissioning windows. Cooling plants, process piping, and power distribution must perform as designed from day one. There is little tolerance for rework. Owners in every sector benefit from planning earlier. Securing qualified partners ahead of peak demand reduces schedule risk. Clear scopes and realistic timelines help projects hold their place in a crowded market.
The Skilled Labor Gap Behind the Data Center Construction Boom
As capital concentrates in data centers, the skilled labor needed to build them is becoming the market’s tightest constraint. Capital alone does not build a data center. Skilled people do, and that is where the market faces its tightest constraint. In a September 2026 survey by the Associated General Contractors of America, 58% of data center contractors reported tougher competition for skilled workers. Hiring demand keeps rising across the sector. Data center job postings jumped 23% in 2025, according to LinkedIn.
The trades these projects rely on take years to develop. Millwrights, riggers, pipefitters, electricians, and steel erectors build their skills through extensive field experience. Many tasks also require specific certifications. Experienced crews cannot be created overnight, even when budgets allow.
Rural sites add another layer of difficulty. Many planned facilities sit far from established labor pools. Contractors must mobilize crews, equipment, and supervision across long distances. Travel, housing, and logistics become part of the project plan.
The labor gap also raises the stakes for safety and quality. Stretched crews and compressed schedules increase the risk of costly errors. Mission-critical facilities cannot absorb those mistakes after startup. Owners need partners who can consistently field qualified people, not just win the bid. Proven crews, documented training, and a strong safety record now separate dependable partners from the rest.
Building Through the Data Center Construction Boom
The data center construction boom shows no sign of slowing. Power demand keeps rising, and investment keeps concentrating in mission-critical facilities. Meanwhile, manufacturing construction has pulled back, and skilled labor remains scarce. These trends create both opportunity and risk. Owners who plan early secure better schedules and stronger teams. Those who wait face tighter labor markets and higher stakes on every project.
Overall, the success of these projects depends on their execution. Equipment must be set right the first time. Piping, rigging, and steel must meet strict standards. Crews must arrive qualified, coordinated, and ready to work safely from mobilization through commissioning.
The same discipline applies well beyond data centers. Manufacturers, processors, and heavy industrial operators compete for the same talent. Every sector benefits from partners with proven depth and a record of reliable delivery. The market will keep shifting as AI infrastructure grows. What stays constant is the value of crews who show up prepared and finish strong.
For owners managing tight schedules, complex systems, and scarce skilled labor, the right industrial partner can determine whether a mission-critical project stays on track. To keep your next project moving, contact HEMI Systems’ nationwide industrial contracting team.